By John Oyuke
Co-operative Bank of Kenya’s profit after tax jumped by 27.2 per cent to Sh27.4 billion in the nine months to September 2026, supported by growth in lending income, higher customer deposits and improved asset quality.
The lender’s net profit rose from Sh21.6 billion recorded in a similar period last year while profit before tax increased by 19.6 per cent to Sh35.9 billion from Sh30 billion. Total assets expanded by 11.3 per cent to Sh907.4 billion, reflecting continued growth in the bank’s balance sheet and lending activities.
The improved earnings were supported by a 22.2 per cent increase in net loans and advances to Sh496.9 billion while customer deposits grew by 14.8 per cent to Sh642.5 billion.
Net interest income increased by 12.7 per cent to Sh51 billion while total operating income rose by 11.6 per cent to Sh75.2 billion, supported by growth in interest income and resilient non-funded income.
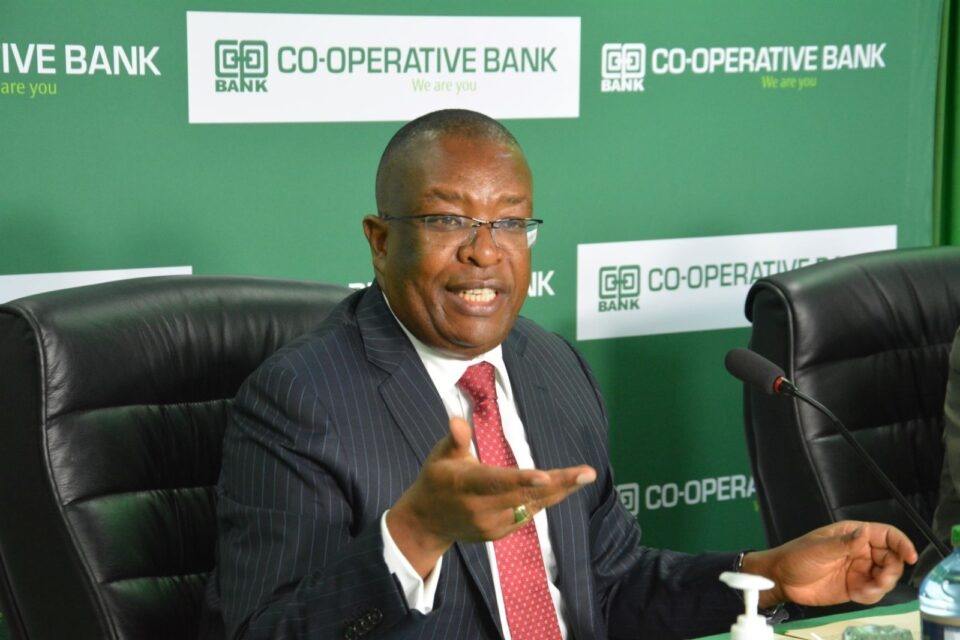
Co-operative Bank Group Managing Director and CEO Dr Gideon Muriuki said the performance reflected progress in implementing the lender’s 2025-2029 Good to Great Strategy and its Soaring Eagle Transformation Agenda.
“The bank maintained control over its operating costs, which increased by 5.3 per cent, slower than the growth in operating income. Its cost-to-income ratio before provisions stood at 46.4 per cent,” he explained.
According to the financial results for the nine months Asset quality also improved, with the non-performing loans ratio declining to 12.9 per cent from 17.1 per cent in September 2025. The cost of risk dropped to 1.4 per cent from 2.5 per cent, while IFRS loan-loss coverage improved to 82.2 per cent from 70.4 per cent.
The bank’s subsidiaries also contributed to the group’s performance. Kingdom Bank recorded a 61.8 per cent increase in profit before tax to Sh1.33 billion, while Co-optrust Investment Services posted a 54.8 per cent growth to Sh966.8 million.
According to Muriuki, Co-operative Bank of South Sudan recorded profit before tax of Sh528 million, compared to Sh93.5 million in the corresponding period last year.
Digital banking remained a key contributor to operations, with approximately 94 per cent of customer transactions processed through alternative delivery channels. The bank’s digital credit platform disbursed Sh66.6 billion during the third quarter, bringing cumulative disbursements since inception to more than Sh568.5 billion.
E-credit disbursements reached Sh66.6 billion in Q3 2026, with cumulative E-credit loan disbursements now surpassing Sh568.5 billion across 16.2 million customer accounts.
To capture the growing youth market, the bank accelerated its “Ignite” brand proposition during the period, disbursing Sh47.5 billion to empower over 585,000 young entrepreneurs and customers.
The lender also announced an increase in shareholder returns, with its board approving an interim dividend of Sh1.50 per share, representing a 50 per cent increase from Sh1 paid last year.
“With the strong performance, the Board has approved an Interim dividend of Sh1.50 per share (50 per cent growth from 1.00/- per share last year) payable to the shareholders in the company’s register on the close of business on November 25 2026 and will be paid on December 4 2026,” Muriuki disclosed.
