Harambee DT SACCO Society has posted steady financial growth heading into 2026, with total assets rising to Sh41.29 billion and net surplus increasing to Sh1.67 billion, even as liquidity pressures and rising dormant membership signal emerging operational risks.
The savings institution’s latest figures show sustained expansion across key financial indicators, including loans and advances which grew to Sh34.27 billion and member deposits which reached Sh27.56 billion, reflecting continued confidence among members.
Active membership rose to 79,942 in 2025 from 74,991 in 2024, while dormant accounts increased sharply to 4,910, highlighting retention challenges even as the institution expanded its branch network from five to six outlets.
Liquidity levels improved from Sh477 million in 2024 to Sh941 million in 2025, though they remain below earlier benchmarks, underscoring ongoing pressure in meeting short term obligations and funding operational expansion.
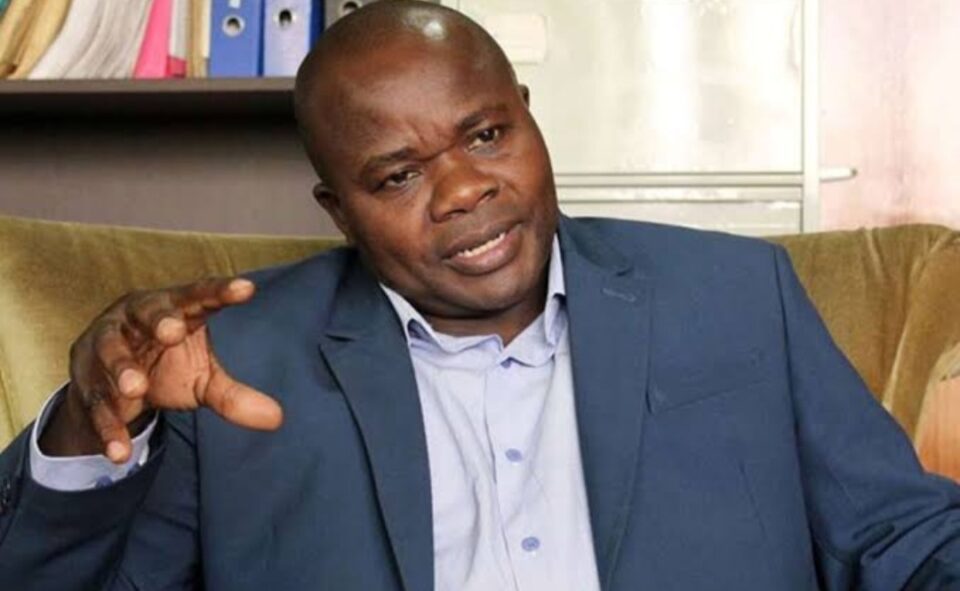
“We promised 10 percent interest on members deposits and delivered 9.1 percent, while maintaining a 15 percent dividend on share capital,” said Chief Executive Officer Dr. George Ochiri, acknowledging the institution’s mixed performance in 2025.
While delivering his remarks during the Annual Delegate Induction and Pre-ADM Symposium in Mombasa, the CEO said total revenue rose to Sh7.21 billion in 2025, driven largely by interest income of Sh5.59 billion, while expenses climbed to Sh3.28 billion, resulting in improved net surplus compared to previous years.
Capital strength also improved, with core capital increasing to Sh6.11 billion and institutional capital reaching Sh3.18 billion, reinforcing the cooperative’s financial stability and capacity to support future lending and investment activities.
Key regulatory ratios remained strong, with core capital to total assets at 14.8 percent and core capital to deposits at 22.2 percent, both exceeding statutory minimum requirements and signaling sound capitalization levels.
However, institutional capital to total assets stood at 7.7 percent, below the recommended threshold, while equity to deposits rose to 8.5 percent, exceeding the advised ceiling and pointing to emerging structural imbalances.
Non-earning assets improved to 8.0 percent of total assets, down from 9.1 percent in 2024, indicating progress in asset quality management despite continued pressure from loan demand and evolving credit risks.
Operationally, the cooperative reported milestones including the opening of a Nanyuki branch, fabrication of a Kisii satellite branch, enhanced digital channels, and improved system uptime to support member transactions and service delivery.
At the same time, several targets were missed, including the planned rollout of five satellite offices and Nairobi branch renovations, alongside persistent liquidity constraints and high member exit rates contributing to rising dormancy.
“Our growth remains anchored on strengthening governance, improving operational efficiency, and protecting members’ savings as we scale our services,” said Dr. Ochiri, outlining the institution’s priorities heading into the next strategic phase.
The cooperative continues to rely heavily on check off systems for membership growth, a model leadership now views as limiting, prompting renewed focus on diversification and expansion into broader market segments.
Investment activity expanded significantly, with financial investments rising to Sh2.35 billion, reflecting a shift toward alternative income streams and reduced dependence on traditional lending as the primary revenue driver.
One notable financing initiative saw the cooperative extend a Sh35 million loan to a member to acquire a fleet of ten new Toyota matatus operating under Sifalines Shuttle, demonstrating support for enterprise growth.
The institution’s strategic evolution has been guided by annual themes since 2019, culminating in the 2026 focus on “Ready for Take-Off,” signaling a transition from recovery and consolidation toward accelerated expansion and innovation.
Internally, management has categorized growth stages using models that assess capital base, membership size, governance quality, and technological adoption, encouraging progression toward larger, more resilient operational structures.
Smaller units are characterized by limited capital, weak governance, and over-reliance on single income streams, while more advanced entities demonstrate diversified investments, strong governance frameworks, and higher levels of dividend recapitalization.
“Our focus now is to move decisively into the next growth phase by deepening technology adoption, expanding our footprint, and enhancing member value across all service channels,” Dr. Ochiri said.
He said the cooperative’s 2026 to 2030 strategy prioritizes financial performance, membership growth, technology and innovation, governance, human resources development, operational efficiency, and expansion of branch banking services.
